
New York / London / Tokyo — November 7, 2026
Global financial markets endured one of their most turbulent weeks of 2026 as a sharp sell-off in artificial intelligence and technology stocks, triggered by the Democratic Party’s decisive gains in the U.S. midterm elections, erased trillions of dollars in market value. The Nasdaq Composite suffered its deepest one-day decline since the April 2025 “Liberation Day” tariff shock, while Asian equity markets posted their worst sessions in years. A modest rebound on Friday offered temporary relief, but investors closed the week confronting a more complex landscape of regulatory uncertainty, elevated energy prices, and shifting growth-inflation dynamics.
The week’s drama centred on the AI trade that has dominated equity markets for much of the year. Strong earnings growth, fueled by massive capital expenditure on data centres, chips, and related infrastructure, had propelled U.S. and Asian technology shares to elevated valuations. That narrative fractured after Democrats secured control of both chambers of Congress. Market participants quickly priced in the prospect of tighter scrutiny of AI development, potential restrictions on data-centre construction (particularly in key states such as Texas), and broader regulatory pressure on Big Tech. The result was a cascading sell-off that began on Wall Street and rapidly spread across Asia and Europe.
Wall Street’s Wild Week: Correction Territory and a Fragile Rebound
U.S. equity markets finished the week of November 2–6 lower across the board. The S&P 500 declined approximately 2.7 per cent, its worst weekly performance since April 2025. The Nasdaq Composite fell about 3.4 per cent, while the Dow Jones Industrial Average slipped a more modest 0.9 per cent. Thursday’s session was particularly brutal: the Nasdaq plunged roughly 5.5 per cent, wiping an estimated $2.5 trillion from the index alone and contributing to a broader multi-trillion-dollar loss across major benchmarks. The Philadelphia Semiconductor Index dropped more than 12 per cent in a single day at one point, reflecting the acute pain among chipmakers.
Nvidia, the emblematic stock of the AI boom, fell nearly 9 per cent on Thursday before recovering part of those losses on Friday with a gain of about 2.8 per cent. Other AI-linked names, including semiconductor peers and companies tied to data-centre infrastructure, followed a similar pattern of sharp declines followed by partial rebounds. SpaceX shares, for instance, rebounded strongly after earlier losses. By Friday’s close, the S&P 500 stood near 7,376.86, the Nasdaq around 24,579, and the Dow near 51,286.
The sell-off was not purely political. Investors had already grown concerned about the sustainability of AI capital spending. Several large technology companies reported strong top-line growth but also flagged significant free-cash-flow pressures from data-centre investments. Questions about the ultimate return on those outlays, combined with high valuations, created fertile ground for a rapid de-risking once the midterm results introduced a new layer of policy uncertainty.
Friday’s partial recovery was driven by bargain hunting and a sense that the most extreme regulatory fears may have been overdone in the initial reaction. Some strategists noted that AI remains a structural growth theme and that previous pullbacks in the sector have ultimately proven temporary. Still, the Nasdaq entered correction territory (a 10 per cent decline from its recent peak), and the week’s losses left markets more cautious heading into the final stretch of 2026.
Asia Bears the Brunt as Tech Supply Chains Feel the Pain
Asian markets, heavily exposed to the global semiconductor and technology supply chain, suffered even steeper declines. Japan’s Nikkei 225 tumbled approximately 6 per cent on Friday, its largest single-day drop since the April 2025 tariff-related panic, and finished the week down more than 9 per cent in some measures. South Korea’s Kospi also fell about 6 per cent, while Taiwan’s Taiex index experienced extreme volatility, at one point plunging more than 8 per cent before authorities intervened to stabilise trading. Shares of TSMC, Samsung Electronics, SK Hynix, and other key suppliers were among the hardest hit.
The severity of the Asian reaction reflected both the concentration of AI-related manufacturing in the region and the sensitivity of local investors and institutions to shifts in U.S. technology policy. Margin calls and forced selling amplified the declines in several markets. Local authorities in Taiwan and South Korea took steps to ease margin requirements and support liquidity, helping to arrest the freefall by the close of trading on Friday. European markets, less dominated by pure technology names, still declined, with Germany’s DAX falling nearly 2 per cent and broader European indexes retreating 1–1.5 per cent.
Oil, Geopolitics, and the Inflation-Growth Tightrope
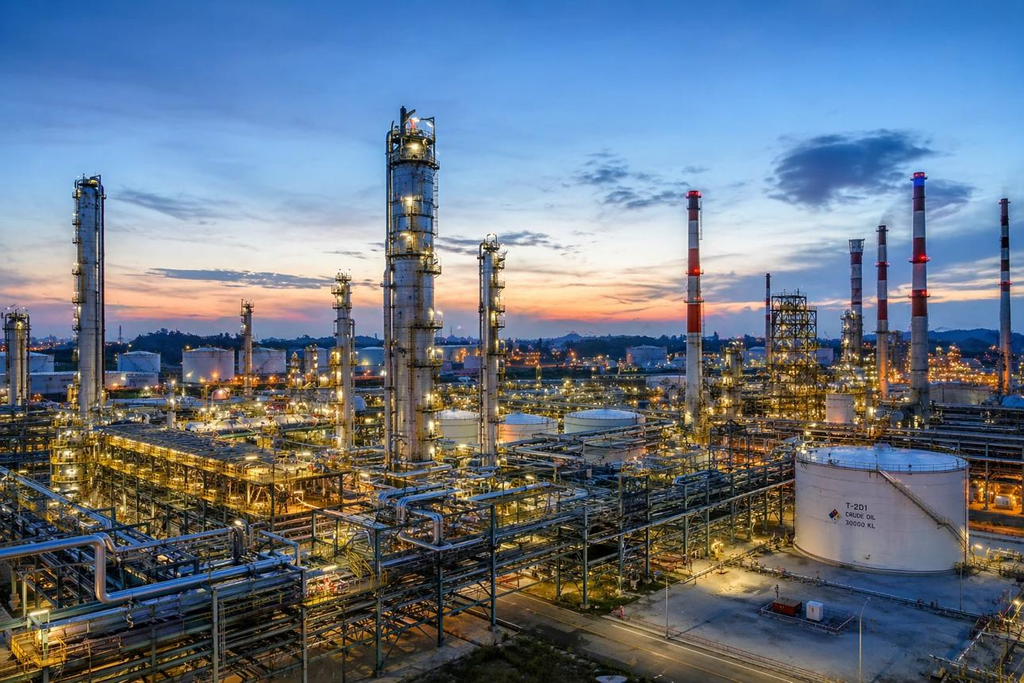
Energy markets provided an additional layer of complexity. Oil prices remained elevated by historical standards after months of tension linked to the Iran conflict, but they eased notably during the week—falling as much as 15 per cent at points—as hopes of de-escalation rose following the U.S. political shift. Brent crude hovered near or slightly below $100 a barrel by week’s end, still substantially higher than levels seen at the start of 2026. Natural gas prices have remained particularly elevated.
The combination of high energy costs, sticky inflation readings, and now tighter financial conditions from the equity sell-off has heightened concerns about a stagflationary environment. Global growth has shown resilience through much of 2026, supported by AI-related investment and solid corporate earnings, with forecasts around 2.7–2.8 per cent for the year. Yet softer European data, rising borrowing costs, and the potential for reduced AI capital expenditure have prompted traders to reassess the growth outlook.
Bond markets reflected the competing forces. Rate-sensitive yields declined in the wake of the equity rout as investors sought safety and reassessed the path of monetary policy. U.S. two-year yields fell, and market pricing for a December Federal Reserve rate hike became less certain, though still elevated. European yields also eased. Gold prices rose on safe-haven demand.
Central Banks Navigate a Narrow Path
Central banks face a delicate balancing act. The Federal Reserve raised rates earlier in the autumn for the first time in three years and has been widely expected to tighten further in December, potentially taking the federal funds rate to the 4.00–4.25 per cent range. Stronger-than-expected U.S. jobs data released late in the week—payrolls rising by 165,000 and unemployment dipping—reinforced the case for continued vigilance on inflation. At the same time, the equity market turmoil and potential growth headwinds from tighter financial conditions and higher energy prices complicate the calculus.
The European Central Bank faces similar tensions. Markets reduced the probability of a December hike as growth concerns mounted, though elevated energy prices keep inflation risks alive. The Bank of Japan continues to navigate its own gradual normalisation path amid domestic considerations. Across major economies, policymakers must weigh the risk of overtightening against the danger of allowing inflation expectations to become unanchored by energy and food price pressures.
Corporate earnings have remained a bright spot. AI-related investment has driven exceptional profit growth in 2026 for technology and semiconductor companies. Broader earnings growth is expected to decelerate in 2027 but remain supportive of equities, according to strategists at major investment banks. Themes of AI, defence, and economic security are seen as durable drivers of diversification and stock selection opportunities in both developed and emerging markets. Valuations in some emerging-market segments have become more attractive after the recent correction.
Broader Business and Finance Developments
Beyond the equity volatility, several other themes shaped the global business landscape. Private credit and alternative asset managers faced scrutiny as some funds adjusted strategies or returned capital after challenging periods. Banking results in various regions showed resilience, with certain institutions posting strong profit growth. In Asia, corporate activity included ongoing discussions around large-scale deals in robotics and technology, some complicated by geopolitical sensitivities involving China.
Currency markets remained relatively orderly, with the dollar fluctuating on shifting rate expectations and risk sentiment. Emerging-market currencies and equities, already under pressure from the AI-linked sell-off in Asia, continued to lag developed markets in many cases. Commodity markets outside energy showed mixed performance, with precious metals benefiting from uncertainty.
Looking ahead, investors will focus on several key data points and events. U.S. consumer price index figures due in the coming days will be closely watched for clues on the inflation trajectory and the Federal Reserve’s next move. Corporate earnings updates, particularly from remaining technology and semiconductor names, will test whether the AI growth narrative can withstand higher scrutiny and potentially slower capital expenditure. Geopolitical developments related to the Middle East and energy supply will continue to influence oil prices and broader risk appetite. The UN climate summit and various central bank communications will also feature on the calendar.
Strategists emphasise that the AI investment cycle, while experiencing a sharp reality check, is unlikely to reverse entirely. Earnings have been robust, and structural demand for computing power remains significant. However, the era of uncritical enthusiasm appears to have given way to a more selective, returns-focused approach. Political and regulatory developments in the United States will now play a larger role in determining the pace and geography of AI infrastructure build-out.
For global investors, the message from this week is one of heightened uncertainty and the need for diversification. Markets that had been driven by a relatively narrow set of AI and technology leaders are now more sensitive to policy shifts, energy prices, and growth signals. The resilience of corporate earnings and the long-term potential of transformative technologies provide a foundation for recovery, but the path is likely to remain volatile as the world digests the dual shocks of political change in Washington and a recalibration of the AI trade.
In the near term, traders will look for signs that the worst of the forced selling has passed and that bargain hunters are prepared to support key names at lower valuations. Whether the rebound that began on Friday can gain lasting traction will depend on the interplay of incoming economic data, corporate commentary on AI investment plans, and any further clarity—or ambiguity—on the regulatory environment emerging from the new political balance in the United States.
The events of early November 2026 have underscored a familiar truth in financial markets: even the most powerful investment themes are subject to abrupt shifts in sentiment when politics, valuations, and macroeconomic realities collide. As the year draws toward its close, global business, stock markets, and finance stand at an important juncture—still supported by underlying economic strength and technological progress, yet newly reminded of the risks that accompany concentrated bets and rapid policy change.