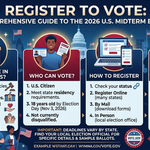


With Election Day just under two weeks away on November 3, 2026, American voters are preparing to deliver a verdict on President Donald Trump’s second-term agenda and the Republican-controlled Congress. Midterm elections traditionally serve as a referendum on the sitting president, and historical patterns strongly favor the opposition party. This cycle appears no exception. Trump’s approval rating has sunk into the high 30s—around 37 to 39 percent in recent aggregates, with disapproval near 60 percent—levels last seen for presidents who suffered significant midterm losses, such as Harry Truman in 1946 and George W. Bush in 2006.
National generic congressional ballot polls show Democrats leading by seven to nine points, a margin consistent with wave elections. Forecast models from independent analysts give Democrats a strong probability of reclaiming the House of Representatives and a competitive, if narrower, chance at flipping the Senate. Control of Congress will shape the final two years of Trump’s term, determining whether the administration can advance priorities on immigration enforcement, tariffs, energy policy, and foreign affairs or face aggressive oversight, investigations, and legislative gridlock.
Republicans currently hold a 53-47 Senate majority. Democrats need a net gain of four seats for an outright majority; a 50-50 split would leave Republicans in control via Vice President JD Vance’s tie-breaking vote. In the House, Republicans hold a slim edge of roughly 220 to 222 seats against 213 to 215 for Democrats (accounting for vacancies and independents), meaning Democrats need only a modest net gain to reach the 218-seat majority threshold. The battlefield has expanded dramatically into traditionally Republican territory, driven by voter frustration over the cost of living, the ongoing conflict with Iran, and uneven perceptions of border security gains.
The Broader Political Climate
Midterms almost always punish the president’s party. Since World War II, the president’s party has lost an average of more than two dozen House seats and several Senate seats in the first midterm of a new term. Trump’s return to office in 2025 after the 2024 election was accompanied by high expectations on economic relief and border control. Early enforcement actions produced a sharp drop in southwest border encounters—preliminary Department of Homeland Security figures showed roughly a 95 percent decline compared with the prior administration—but public attention has shifted to the human and fiscal costs of aggressive interior enforcement, including high-profile incidents involving Immigration and Customs Enforcement agents.
Simultaneously, household finances remain strained. Polls consistently rank the cost of living—groceries, gasoline, housing, and healthcare—as the dominant issue for voters of both parties. Trump’s tariff policies, intended to reshape trade and protect domestic industry, have contributed to higher prices on imported goods in the view of many economists and consumers. The conflict with Iran, which closed the Strait of Hormuz for a period and drove up energy costs, has further complicated the economic picture and raised questions about congressional authorization for military action.
Trump’s personal unpopularity has become a central organizing force. Democrats have framed the election as a check on executive power, while Republicans have sought to nationalize the race around border security achievements, crime, and cultural issues. Yet the intensity of anti-Trump sentiment among independents and moderate Republicans has widened the map. Districts and states that Trump carried by double digits in 2024 are now competitive. Outside spending has reached record levels in several contests, with hundreds of millions of dollars flowing into television, digital, and ground operations.
House of Representatives: Democrats Favored for a Majority
Control of the House looks increasingly likely to shift. Nonpartisan forecasters, including the Cook Political Report, Sabato’s Crystal Ball, and independent models such as those tracked by Decision Desk HQ and Silver Bulletin, project Democratic gains in the range of 15 to 25 seats. Some simulations put Democrats’ probability of winning the chamber above 80 or even 90 percent, with expected seat totals in the mid-220s.
The competitive landscape now includes more than 40 races rated as toss-ups or leans by major rating services. Many of these are Republican-held seats in the Midwest, Sun Belt, and suburban districts where economic discontent is acute. In Ohio, Nebraska, Kansas, and Iowa—states with competitive Senate races as well—several House districts that were once considered safe have tightened. Montana’s 1st District, which Trump won by a comfortable margin in 2024, has moved into the toss-up column. Similar shifts have occurred in Michigan, Pennsylvania, Arizona, California, and Florida.
Redistricting completed in several states after the 2024 cycle altered the baseline. Republicans gained some seats through maps in certain states, while Democrats offset those gains through favorable lines in California and elsewhere. The net effect has not insulated the GOP from the national environment. Democratic challengers have focused relentlessly on affordability, healthcare costs, and what they describe as overreach in immigration enforcement. Republican incumbents and candidates emphasize crime reduction, border security metrics, and tax and regulatory relief.
Suburban and independent voters appear to be the decisive groups. Early voting data and internal party tracking suggest elevated Democratic enthusiasm, particularly among women, younger voters, and college-educated suburbanites. Rural and working-class white voters remain more solidly Republican, but the intensity gap has narrowed compared with 2024. A Democratic House majority would install a new speaker and committee chairs prepared to issue subpoenas, block or amend administration priorities, and force difficult votes on spending and investigations.
Senate: A Tighter but Expanding Battlefield
The Senate contest is more balanced on paper yet has grown more favorable to Democrats than expected at the start of the cycle. Republicans defend a larger number of seats, and the map includes several states Trump won handily. Democrats are defending open or competitive seats in Michigan, Georgia, Minnesota, and New Hampshire while targeting Republican-held seats in Maine, Alaska, Ohio, Texas, Iowa, Kansas, North Carolina, and even South Carolina and Nebraska.
Key races illustrate the volatility:
- In Maine, Republican Sen. Susan Collins, a long-serving moderate who has sometimes broken with Trump, faces Democratic former state Senate President Troy Jackson. Polls have shown Jackson with a narrow lead in a state Trump lost in 2024. Collins has kept her distance from the president on the campaign trail.
- Alaska features Republican Sen. Dan Sullivan against former Democratic Rep. Mary Peltola. Ranked-choice voting and Peltola’s personal popularity among independents have made this a genuine toss-up or lean Democratic contest.
- Ohio pits former Democratic Sen. Sherrod Brown against Republican Sen. Jon Husted (appointed or elected in the interim). Brown has led in most recent surveys by low-to-mid single digits in a state Trump carried comfortably. The race has attracted enormous outside spending, including from cryptocurrency interests supporting Husted.
- Texas offers one of the cycle’s biggest surprises: Democratic state Rep. James Talarico, a progressive Christian, against Trump-backed Attorney General Ken Paxton. Paxton’s legal controversies and Talarico’s fundraising prowess have turned a deep-red state into a battleground. Recent polls show the race within the margin of error.
- Iowa (open seat after Sen. Joni Ernst’s retirement) and Kansas (Sen. Roger Marshall) have both tightened dramatically. Democratic candidates have closed gaps that once looked insurmountable.
- North Carolina, where former Democratic Gov. Roy Cooper seeks the seat being vacated by Republican Thom Tillis, has leaned Democratic in late polling. Georgia’s Sen. Jon Ossoff has maintained a clearer lead over his Republican challenger.
Cook Political Report and other raters list roughly seven to ten seats as pure toss-ups, with additional leans that could move. Prediction markets and forecasting models give Democrats between roughly 50 and 65 percent odds of netting the four seats needed for control, though outcomes remain sensitive to turnout and late shifts.
Republican advantages include superior organization in some rural areas and the structural lean of the map. Democratic advantages stem from the national environment, candidate quality in several races, and high-intensity opposition to Trump among key demographics.
Defining Issues: Economy, Immigration, and Foreign Policy
Three issues dominate voter conversations: affordability, immigration, and the Iran conflict, with secondary concerns around healthcare, abortion, crime, and emerging technologies.
The economy ranks first for the large majority of voters. Eighty-four percent of registered voters in a recent Pew survey called it “very important” to their congressional vote. Cost of living pressures—food, energy, housing, and insurance—have not fully subsided despite earlier progress on inflation. Tariffs and supply-chain effects from the Iran conflict have kept gasoline and certain goods elevated. Democrats argue that Republican policies have failed working families; Republicans counter that Democratic spending and regulation are the root causes and point to wage growth and energy production gains.
Immigration remains highly polarized. Republicans highlight the dramatic reduction in illegal crossings and portray Democrats as soft on enforcement. Democrats and some independents criticize the scale and methods of interior enforcement, citing reports of aggressive tactics and impacts on legal immigrants and communities. High-profile incidents have shifted some public opinion, particularly in suburban areas, toward the view that the crackdown has gone too far even as border metrics improved.
The war with Iran has injected foreign policy into domestic races more forcefully than usual. Gasoline price spikes and questions about the duration and authorization of U.S. involvement have given Democrats an opening to attack Trump’s “America First” credentials. Abortion continues to motivate Democratic base voters, especially women, in states with restrictive laws, though it ranks lower nationally than in 2022. Artificial intelligence, data centers, and cryptocurrency regulation have surfaced in specific contests—most notably Ohio—where local economic impacts and energy demands are tangible.
Healthcare costs, education, and crime round out the list. Partisan differences are sharp: Republican voters prioritize immigration and crime more heavily; Democratic voters place greater weight on healthcare, democracy concerns, and climate.
Campaign Dynamics and the Road to November 3
Campaign spending has shattered previous records in several battlegrounds. Outside groups on both sides have blanketed the airwaves and digital platforms. Democratic-aligned PACs have poured resources into expanding the map, while Republican committees and pro-Trump organizations have scrambled to defend seats once considered safe. Candidate quality has mattered: Democrats fielded relatively strong nominees in several red-state contests, while some Republican primaries produced controversial or less polished standard-bearers.
Turnout will be decisive. Midterms typically see lower participation than presidential years, but early voting patterns and registration data suggest heightened engagement. Democrats hope to recreate the enthusiasm of 2018; Republicans aim to mobilize the 2024 coalition of rural, working-class, and non-college voters. Independent voters, particularly in the suburbs, are expected to swing the closest races.
State-level contests for governor and legislatures add further stakes. Several gubernatorial races in Ohio, Texas, and elsewhere have become competitive, potentially affecting redistricting and policy agendas for years.
Implications for Governance
A Democratic House would immediately alter the balance of power. Committee investigations into administration policies, spending priorities, and personnel could consume significant bandwidth. Legislation preferred by the White House would face higher hurdles. A Democratic Senate would make confirmations more difficult and could block or force modifications to judicial and executive appointments.
Even if Republicans retain one or both chambers, the margin is likely to be thinner, limiting the ability to pursue ambitious agenda items without bipartisan support. Unified Republican control would allow Trump to press forward more aggressively; divided government would enforce compromise or stalemate.
Voters appear broadly dissatisfied with the direction of the country. Right-track/wrong-track numbers remain deeply negative. The midterms offer a mechanism for course correction short of the next presidential election. Whether that correction produces a modest adjustment or a more sweeping realignment will become clear on the night of November 3 and in the days of counting that follow.
As early voting continues and the final debates and advertising blitzes unfold, the central question remains whether the combination of economic pressure, foreign policy controversy, and presidential unpopularity will produce the kind of broad backlash that has reshaped Congress in previous midterm cycles. The answer will determine the political terrain for the remainder of Trump’s term and set the stage for 2028.