
Global equity markets closed Friday, October 30, 2026, sharply lower, with technology shares leading a broad sell-off that erased more than $1 trillion in market value from the sector and pushed the Nasdaq Composite to its steepest one-day decline since early June. The move capped a difficult October for growth stocks. It intensified investor questions about whether the enormous capital being poured into artificial intelligence infrastructure will generate adequate returns quickly enough to justify current valuations.
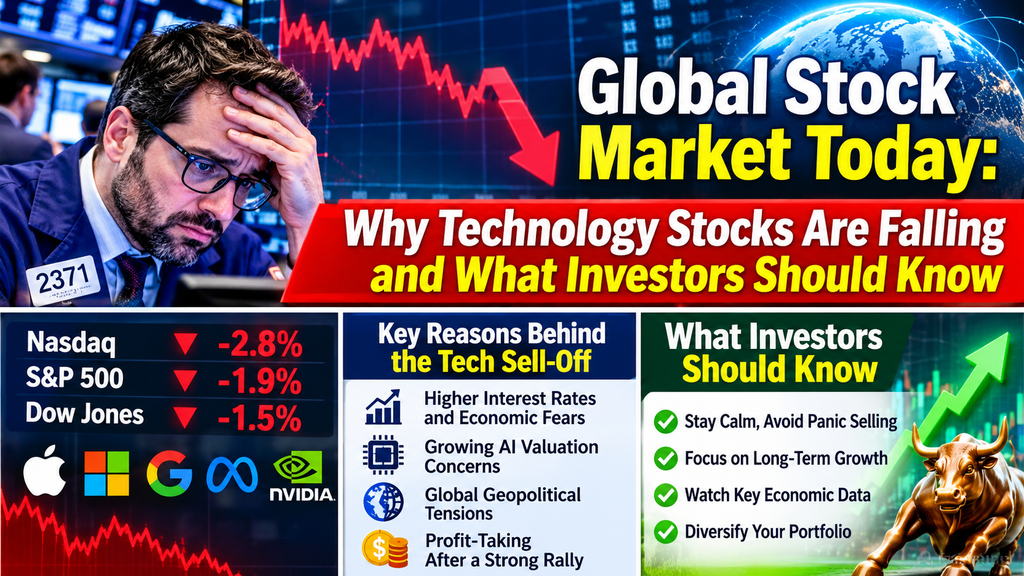
Wall Street’s major indexes all finished in the red. The Dow Jones Industrial Average fell 572.25 points, or 1.09 per cent, to 51,770.31. The S&P 500 dropped 140.32 points, or 1.82 per cent, to 7,580.07—its worst single-day performance since June. The tech-heavy Nasdaq Composite tumbled 747.73 points, or 2.86 per cent, to 25,437.00. The Nasdaq has now declined roughly 7.8 per cent from its record closing high set on October 6 and posted its weakest monthly performance since March 2025. The Russell 2000 of smaller companies also finished lower, falling about 1.7 per cent.
The sell-off was concentrated in technology and semiconductor names. An index of chipmakers fell more than 7 per cent on the day and is down more than 15 per cent for the month. Nvidia shares declined about 4.2 per cent, Advanced Micro Devices dropped nearly 11 per cent, and several other semiconductor and data-centre related stocks posted double-digit percentage losses. The damage was not limited to the United States. Asian markets had already turned lower earlier in the session, with South Korea’s Kospi falling more than 3 per cent and Japan’s Nikkei 225 dropping about 2.1 per cent. European indexes were mixed but generally softer as the AI-related pressure from New York filtered through.
The Spark: Earnings and the AI Cash-Burn Narrative
The immediate catalysts were disappointing quarterly results and forward guidance from Intel and Amazon, released after the market closed on Thursday, layered on top of an already bruising reaction to Alphabet’s results the previous day.
Intel shares plunged as much as 30 per cent—its worst one-day decline in decades, dating back to at least 1974 in some data sets—after the company issued fourth-quarter revenue guidance well below Wall Street expectations. Management pointed to a prolonged slowdown in personal-computer demand, exacerbated by elevated memory-chip prices driven in part by the same AI build-out that has been a major theme for investors. Even though Intel’s data-centre and AI-related revenue rose sharply, the weak consumer PC outlook and the sheer scale of the guidance miss overwhelmed any positives.
Amazon shares also came under pressure after the company reported that it had burned through $42.4 billion in free cash flow over the trailing twelve months while ramping capital expenditures, largely for AI-related infrastructure and capacity. Cloud growth remained strong, but the combination of higher spending and softer growth in certain core areas left investors wanting clearer evidence that the heavy investment would translate into durable profits. Amazon pared some of its early losses as the session progressed, yet the broader message about cash burn stuck.
Alphabet, parent of Google, had already suffered its largest single-day percentage decline on record on Thursday after reporting weaker-than-expected search advertising results and confirming that massive AI spending had turned free cash flow negative. Shares continued to drift lower on Friday. Investors focused less on the still-impressive growth in cloud services and more on signs that AI features might be pressuring traditional search monetisation while capital intensity soared.
Taken together, the reports crystallised a growing concern that had been building throughout October: Big Tech and its suppliers are committing hundreds of billions of dollars—estimates for the major hyperscalers alone run into the high hundreds of billions for 2026—to data centres, chips, power, and related infrastructure, yet the path to commensurate returns remains uncertain and may stretch longer than many bulls had assumed. Analysts and strategists noted that investors are no longer satisfied with the narrative of “spend now, profits later.” They want clearer evidence that the spending is productive and that core businesses are not being cannibalised or stretched in the process.
Broader Market Context and Rotation
The technology rout occurred against a backdrop of still-elevated interest rates, mixed economic signals, and geopolitical tension. The Federal Reserve had held rates steady earlier in the week, offering little fresh guidance on the timing of any future moves. Bond yields fell on Friday as investors sought safety; the benchmark 10-year Treasury yield declined several basis points. Oil prices, by contrast, rose on continued supply concerns linked to the conflict involving Iran and attacks on Russian refining capacity.
Market breadth told a more nuanced story than the headline index declines. While the megacap technology names that have driven much of the year’s gains suffered heavy losses, a majority of stocks in the S&P 500 had actually been positive for the month of October heading into the final session. Energy and certain industrial and defensive names held up better or advanced, pointing to a rotation out of the most crowded AI-related trades rather than a wholesale collapse in risk appetite. Small- and mid-cap stocks had shown relative resilience in prior sessions, though they too finished lower on Friday.
Crypto markets added another layer of unease. Reports of a massive cyberattack on Binance, estimated at around $6.3 billion, sent Bitcoin and other digital assets lower and pressured related stocks. The episode, while separate from the AI narrative, reinforced a risk-off tone.
Outside the United States, the picture was similarly mixed but skewed negative for technology-heavy markets. Chinese equity indexes have struggled for months amid concerns about demand for AI-related hardware and a broader slowdown in the data-centre equipment cycle. South Korean and Taiwanese chip and technology stocks faced particular pressure given their central role in the global semiconductor supply chain.
Why Technology Stocks Are Falling: The Core Drivers
Several interlocking factors explain the intensity of the sell-off.
First is the sheer scale of capital expenditure. Companies such as Amazon, Alphabet, Microsoft, Meta, and Oracle have dramatically increased spending on servers, custom chips, networking, power, and cooling. When free cash flow turns negative, or guidance implies continued heavy outlays without a matching acceleration in monetisation, investors reassess valuation multiples that had been predicated on rapid and visible returns.
Second is evidence of strain in adjacent markets. Intel’s commentary on PC demand being squeezed by high memory prices is a concrete example of how the AI boom can create shortages and higher costs elsewhere in the technology ecosystem, potentially slowing other end markets.
Third is the question of competitive dynamics and monetisation. Alphabet’s search advertising miss raised the possibility that AI-generated answers and summaries could reduce traditional click-through rates and ad inventory quality. Similar concerns have surfaced around referral traffic to other platforms. At the same time, enterprise customers of AI services are reportedly becoming more disciplined about token usage and spending, suggesting that the early phase of unconstrained experimentation may be giving way to more measured adoption.
Fourth is valuation and positioning. After a multi-year run in which a relatively small group of technology and semiconductor stocks accounted for a large share of index gains, many of those names were priced for near-perfection. Any disappointment, or even the absence of accelerating good news, can trigger rapid de-risking, especially when leveraged and momentum-oriented strategies are involved.
Fifth is the broader macro environment. Higher-for-longer interest rates raise the discount rate applied to distant cash flows and increase the opportunity cost of capital-intensive projects. Geopolitical risks, energy-price volatility, and uncertainty around the U.S. midterm elections have further encouraged caution.
What Investors Should Know
For investors, the current episode is less a verdict on the long-term potential of artificial intelligence than a reminder that transformative technologies often follow a classic cycle of exuberance, overspending, scepticism, and eventual more sustainable growth. Several practical points stand out.
Concentration risk remains elevated. Portfolios heavily tilted toward the largest technology and semiconductor names have experienced outsized volatility in recent weeks. Diversification across sectors, market capitalisations, and geographies can reduce the impact of a single-theme reversal.
Cash-flow discipline is now under sharper scrutiny. Companies that can demonstrate a credible path from heavy capital spending to improving free cash flow and returns on invested capital are likely to be rewarded; those that cannot may face continued multiple compression. Upcoming earnings from other major technology firms, including Apple in the near term and Nvidia later in November, will be watched closely for any signs of softening demand or further escalation in spending plans.
The rotation toward value, industrials, energy, and certain financials that has been underway in fits and starts may have further room to run if the AI narrative continues to face questions. At the same time, any clearer evidence that AI applications are delivering measurable productivity gains or new revenue streams could quickly reverse sentiment.
Interest-rate and geopolitical developments will remain important swing factors. A more dovish shift from the Federal Reserve or a de-escalation in energy-related risks could support broader risk assets, including technology shares. Conversely, sticky inflation or further supply shocks would keep pressure on valuations.
Valuations after the recent decline are more reasonable than they were at the early-October peaks, but they are not uniformly cheap. Selective opportunities may exist among high-quality technology companies whose long-term competitive positions remain intact and whose balance sheets can support continued investment without excessive dilution or leverage. At the same time, speculative names with thin earnings power or high dependence on continued easy capital may face a more prolonged period of digestion.
Finally, history suggests that periods of sharp sector rotation and narrative reassessment are common in long bull markets. The technology sector has delivered substantial gains over the past several years precisely because of genuine advances in computing, software, and now AI. The current pullback does not erase those fundamentals, but it does force a more rigorous evaluation of timelines, capital intensity, and competitive sustainability.
Looking Ahead
Markets enter November with the Nasdaq still within striking distance of correction territory, and investor attention focused on the next wave of corporate reports, central-bank commentary, and political developments. The AI investment cycle is far from over; the scale of committed capital and the technological progress already achieved ensure that spending will remain elevated for years. What has changed is the market’s willingness to accept that spending without clearer evidence of economic returns.
For now, the message from Friday’s session is unambiguous: technology stocks are falling because investors are demanding proof that the AI boom will translate into profits rather than simply into higher capital budgets. How companies respond in the coming quarters—through tighter spending, faster monetisation, or clearer communication of the return profile—will determine whether the current sell-off proves to be a healthy pause or the start of a more extended period of underperformance for the sector that has dominated market returns for much of the past decade.
Investors who maintain a long-term perspective, manage concentration carefully, and remain selective about valuation and cash-flow quality are likely best positioned to navigate the uncertainty. The technology sector’s capacity for innovation remains undiminished; the market’s patience for unproven spending, however, has clearly diminished.