

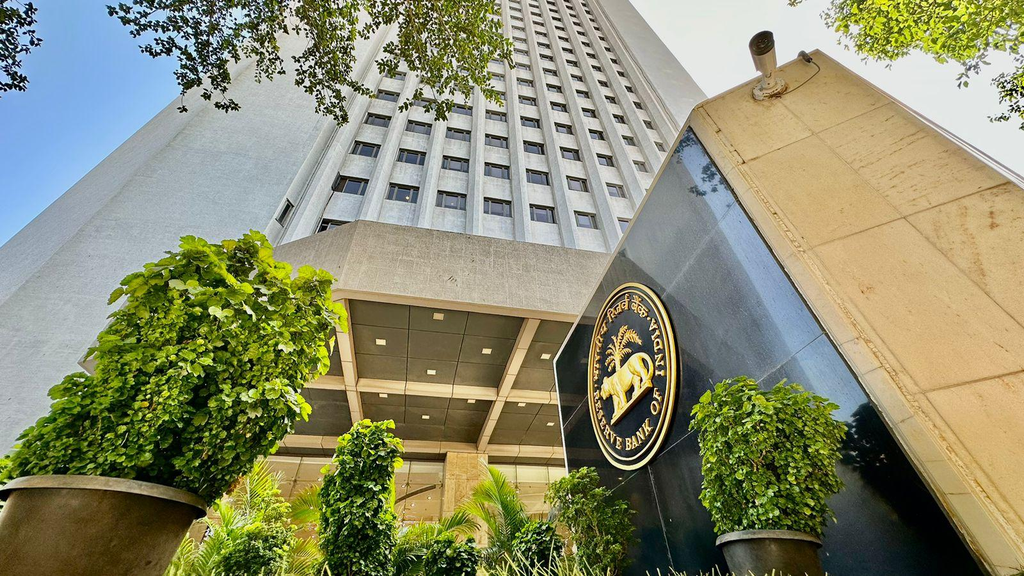
New Delhi, October 11, 2026 – In a decisive shift after nearly four years, the Reserve Bank of India’s Monetary Policy Committee (MPC) on October 7 raised the policy repo rate by 25 basis points to 5.50 per cent. The unanimous decision, the first hike since February 2023, ends a prolonged phase of monetary easing and signals the start of a calibrated tightening cycle. The Standing Deposit Facility rate moved to 5.25 per cent, while the Marginal Standing Facility rate and Bank Rate rose to 5.75 per cent. The MPC also changed its stance from neutral to “calibrated tightening,” making clear that rate cuts are off the table in the near term.
Governor Sanjay Malhotra, who chairs the six-member panel, said future actions would depend on evolving growth-inflation dynamics. Policy options ahead are limited to further hikes or a pause. The move comes against a backdrop of resilient domestic growth, rising inflationary pressures from food, fuel and broader price transmission, elevated global oil prices linked to geopolitical tensions in West Asia, a weaker rupee, and deficient monsoon conditions.
The RBI revised its real GDP growth forecast for 2026-27 upward to 7.1 per cent from 6.7 per cent earlier, reflecting strong private consumption, fixed investment, manufacturing momentum and buoyant services exports. Quarterly projections stand at 7.2 per cent for Q2, 6.9 per cent for Q3 and 6.8 per cent for Q4. For Q1 of 2027-28, growth is projected at 7.1 per cent, with risks assessed as evenly balanced. Headline CPI inflation for 2026-27 was raised to 5.2 per cent, with quarterly estimates of 4.9 per cent in Q2, 6.0 per cent in Q3 and 5.7 per cent in Q4. Core inflation is projected at 4.4 per cent. Inflation is expected to average nearly 5.8 per cent over the next three quarters.
This policy pivot has immediate and differentiated implications for home-loan borrowers and fixed-deposit (FD) investors.
Impact on Home Loan Borrowers: EMIs Set to Rise
Most floating-rate home loans in India, especially those sanctioned after October 2019, are linked to external benchmarks such as the repo rate under the External Benchmark Linked Rate (EBLR) or Repo Linked Lending Rate (RLLR) framework. A 25-basis-point rise in the repo rate typically translates into an equivalent increase in the lending rate for these borrowers, subject to the bank’s spread and the contractual reset cycle (usually every three months).
Several public-sector banks, including Punjab National Bank, Bank of Baroda, Bank of India and Indian Bank, have already revised their repo-linked benchmark rates upward by 25 basis points effective from early October. Existing borrowers will feel the impact at their next reset date rather than overnight.
Illustrative calculations show a measurable rise in monthly outgoings. For a ₹50-lakh home loan with a 20-year tenure at an illustrative pre-hike rate of around 8.50 per cent, the EMI rises by approximately ₹780–₹800 per month after a 25-basis-point increase, adding roughly ₹1.9 lakh in total interest over the full tenure if the higher rate persists. On a ₹50-lakh loan at 7.50 per cent over 25 years, the EMI increase is estimated at around ₹817 per month, translating into roughly ₹2.45 lakh in additional interest. Smaller loans see proportionally lower absolute increases: about ₹380–₹650 extra per month on outstanding amounts of ₹25–40 lakh.
Banks often keep the EMI unchanged by default and extend the loan tenure instead. This choice can prove costlier in the long run. For a ₹40-lakh outstanding loan with 18 years remaining, stretching the tenure by several months to absorb a 25-basis-point rise may add significantly more total interest than raising the EMI by a few hundred rupees. Borrowers are advised to request an EMI increase in writing if cash flows permit, or to make partial prepayments to neutralise the impact.
MCLR-linked loans (still held by a minority of older borrowers) will respond more slowly, as resets depend on the bank’s internal cost-of-funds calculations and can occur annually. Fixed-rate loans remain insulated until the fixed period ends. New home-loan applicants will face higher pricing immediately, particularly during the festive season when demand is typically strong.
The cumulative effect of the 2025 easing cycle (125 basis points of cuts that brought the repo rate down from 6.50 per cent to 5.25 per cent) has provided substantial relief. The October hike partially reverses that benefit. With the stance now at calibrated tightening, markets and analysts see the possibility of further gradual increases depending on how inflation evolves, especially if food and energy pressures persist or second-round effects become more evident.
Borrowers can mitigate the impact by reviewing their loan accounts promptly, exploring balance-transfer options if better spreads are available elsewhere, and prioritising prepayments when surplus funds arise. Maintaining an emergency buffer becomes more important as monthly obligations edge higher.
Impact on FD Investors: Modest Upside with a Lag
For savers, the rate hike is broadly positive, though transmission to deposit rates is neither automatic nor complete. Existing fixed deposits continue to earn the contracted rate until maturity; the policy change has no retroactive effect. The benefit accrues to new deposits and renewals.
Banks raise deposit rates based on their own liquidity needs, competition for funds and overall funding strategy. A 25-basis-point repo hike does not guarantee an identical rise in FD rates. Current term-deposit rates for tenures above one year generally range between 6.00 and 6.75 per cent at major banks, with small finance banks and some private lenders offering higher yields. Senior citizens typically receive an additional 0.25–0.50 per cent.
Analysts expect deposit rates to firm up gradually. Even a partial pass-through of 15–25 basis points on a ₹10-lakh deposit could generate an extra ₹1,500–₹2,500 in annual interest before tax. Investors with maturing FDs in the coming weeks may benefit from waiting a short period to compare revised rate charts across banks rather than renewing immediately at existing levels. Laddering deposits across different tenures remains a prudent strategy to manage reinvestment risk if further hikes materialise.
Savings account rates, already low at around 2.50–3.00 per cent at most banks, are unlikely to see meaningful change. Debt mutual fund investors, particularly those in shorter-duration and floating-rate categories, may experience some mark-to-market pressure in the near term as yields adjust upward, but longer-term returns could improve as higher yields get locked in.
Broader Context and Outlook
The RBI’s decision reflects a careful balancing act. Domestic growth remains robust—Q1 GDP expanded 7.8 per cent—and the upward revision in the full-year forecast underscores confidence in private demand and investment. At the same time, inflation is no longer as benign as it appeared in 2025. Food price pressures have broadened, core inflation has edged higher, and global energy and commodity costs remain elevated amid unresolved geopolitical tensions.
The “calibrated tightening” stance explicitly rules out near-term cuts while leaving the extent of the cycle open. Governor Malhotra emphasised that the duration and magnitude of any further hikes will hinge on underlying inflation, the breadth of price pressures, second-round effects, and demand-side impulses. The next MPC meeting is scheduled for December 2–4, 2026.
For households, the message is clear. Borrowers with floating-rate home loans should prepare for higher EMIs or longer tenures and consider proactive steps such as EMI increases or prepayments. FD investors can look forward to modestly better returns on fresh and renewed deposits, though the gains will arrive with a lag and vary by bank. In an environment of resilient growth but rising price risks, the RBI has prioritised anchoring inflation expectations while preserving the growth momentum that has characterised the Indian economy in recent quarters.
The October 2026 policy marks the end of the low-rate comfort zone for many borrowers and the beginning of a more cautious monetary phase. Careful financial planning—reviewing loan terms, optimising deposit ladders, and maintaining liquidity buffers—will help households navigate the evolving interest-rate landscape in the months ahead.
Disclaimer: This report is for general informational purposes only and does not constitute financial, investment, or professional advice. Interest rates, EMI calculations, and FD returns are illustrative and may vary based on individual loan terms, bank policies, and market conditions. Readers should consult their bank or a qualified advisor before making any financial decisions. Data is based on information available as of October 2026 and is subject to change.